
Foreign client से payment आई? पहले GST export की सभी शर्तें जाँचें
Freelancer, designer, software consultant या agency को विदेश से project मिला तो खुशी की बात है। लेकिन केवल ग्राहक का address विदेश में होना या पैसा foreign currency में आना अपने-आप GST में “export of services” नहीं बनाता। Recipient कौन है, service का place of supply कहाँ है, आप intermediary तो नहीं, और payment कैसे मिला—इन सबका record साथ देखकर फैसला करें।
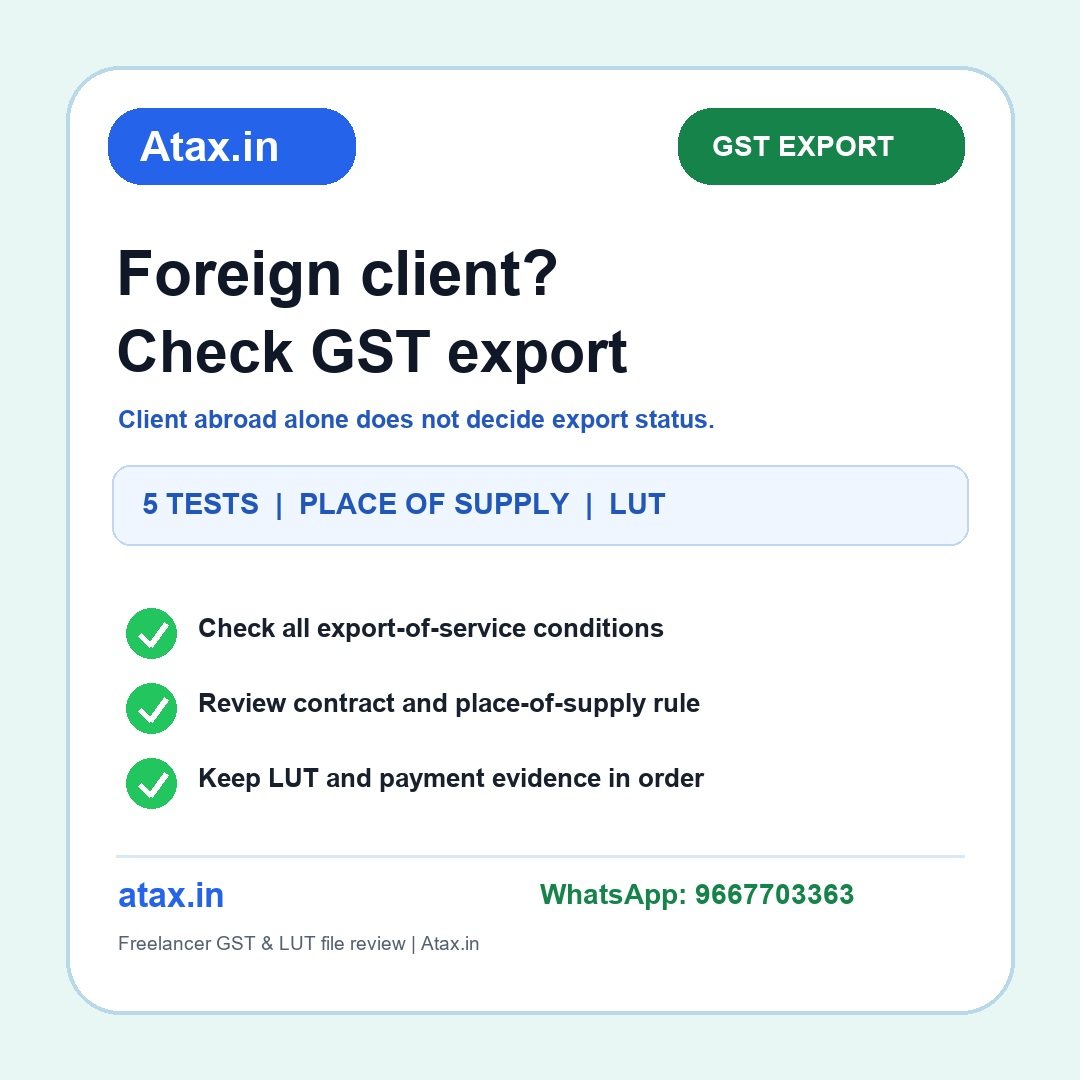
Export of service की पाँचों शर्तें
IGST Act की Section 2(6) में सेवा तभी export मानी जाती है जब सभी आवश्यक कसौटियाँ पूरी हों:
- सेवा देने वाला supplier भारत में located हो।
- सेवा पाने वाला recipient भारत के बाहर located हो। Contract, invoice और वास्तविक customer details देखें।
- उस service का place of supply भारत के बाहर हो। सामान्य cross-border services में recipient-location rule हो सकता है, लेकिन Section 13 के विशेष नियम पहले जाँचने होते हैं।
- Payment convertible foreign exchange में, या RBI जहाँ अनुमति दे वहाँ Indian rupees में, प्राप्त हुआ हो। Payment gateway/platform की settlement advice और bank credit trail रखें।
- Supplier और recipient केवल एक ही व्यक्ति की अलग-अलग establishments न हों, जैसा कानून में distinct person बताया गया है।
किसी एक condition में समस्या हो तो export treatment और invoice/GST reporting को फिर से जाँचना चाहिए।
एक छोटा उदाहरण: consultant बनाम intermediary
मान लें भारत में बैठा web developer सीधे US client से contract करता है, उसी client को काम देता है और deliverables/fee उसके अपने agreement में हैं। यह export हो सकता है, लेकिन recipient-location, service-specific place-of-supply, payment और बाकी सभी शर्तें फिर भी verify होंगी।
दूसरी ओर, यदि कोई व्यक्ति दो parties के बीच ग्राहक/सेवा arrange करके commission ले रहा है, तो वह “intermediary service” के दायरे में आता है या नहीं, यह facts और contract से तय होगा। IGST Act में intermediary place-of-supply का विशेष नियम है; ऐसी स्थिति में place of supply भारत में आ सकता है और export की शर्त पूरी न हो। केवल “consulting” या “marketing” नाम लिख देने से classification तय नहीं होती।
Payment आने से पहले और बाद की checklist
- Signed agreement, work order या platform terms में service, customer entity, fee, milestone और deliverables साफ रखें।
- Invoice में foreign recipient का सही legal name/address, service description, currency और लागू export declaration रखें। Exact wording और tax treatment अपनी supply तथा current rules से confirm करें।
- Bank credit advice, inward remittance advice/FIRA/FIRC जहाँ उपलब्ध हो, gateway settlement statement और fees/conversion calculation सुरक्षित रखें। केवल payment screenshot पर निर्भर न रहें।
- यदि registered supplier export बिना IGST करना चाहता है, तो export शुरू करने से पहले applicable LUT/bond requirement और portal acknowledgement जाँचें। Rule 96A में RFD-11 तथा non-realisation के समय-सीमा संबंधी दायित्व हैं; due date/extension का अलग review करें।
- GSTR-1 में export invoices और GSTR-3B/books में turnover का period-wise मिलान करें। LUT का होना अपने-आप export eligibility या refund entitlement तय नहीं करता।
- GST registration की applicability को turnover, inter-State supply rules और relevant exemptions के अनुसार अलग जाँचें; यह export की पाँच कसौटियों से अलग सवाल है।
LUT किस काम आता है?
पहले export eligibility तय करें। उसके बाद, जो registered person eligible export supply को बिना IGST के करना चाहता है, उसके लिए नियम के अनुसार bond या Letter of Undertaking (LUT), Form GST RFD-11, prior to export furnish करने की व्यवस्था है। LUT एक undertaking है; यह न तो गलत place-of-supply को बदलता है, न हर freelancer को स्वतः GST registration से छूट देता है, न refund की गारंटी है।
यदि निर्धारित समय तक export payment प्राप्त न हो, तो Rule 96A के तहत आगे का tax/interest परिणाम आ सकता है; rule में RBI द्वारा अनुमत Indian-rupee receipt को भी मान्यता दी गई है। अपने invoice date, receipt date, permitted mode और किसी extension की applicability समय रहते जाँचें।
Atax review के लिए ये कागज़ साथ रखें
- GST registration certificate/portal profile और applicable LUT acknowledgement/ARN;
- Client contract, purchase order, scope of work और deliverable/acceptance trail;
- Issued invoices, credit notes और export invoice register;
- Bank statements, inward-remittance advice, payment-gateway settlement तथा exchange/conversion details;
- GSTR-1, GSTR-3B, sales ledger और books reconciliation;
- यदि service agent/platform के जरिए है, तो platform agreement, commission terms और यह record कि actual service किसने किसको दी।
आम सवाल
क्या foreign client होना ही export साबित करता है?
नहीं। Section 2(6) की सभी शर्तें—खासकर place of supply और service relationship—जाँचनी होती हैं।
अगर पैसा INR में आया तो export नहीं होगा?
कानून RBI द्वारा अनुमत स्थितियों में Indian rupees receipt को मानता है। Payment route, bank evidence और applicable permission की पुष्टि करें; केवल currency देखकर निष्कर्ष न निकालें।
क्या हर freelancer को LUT लेना होगा?
LUT का प्रश्न उस registered person के लिए आता है जो applicable option के तहत export बिना IGST करना चाहता है। पहले registration applicability, export status और chosen tax route देखना जरूरी है।
क्या LUT मिलते ही refund पक्का है?
नहीं। LUT बिना IGST export का compliance document है। Refund की पात्रता, eligible ITC, records और filing conditions अलग से पूरी करनी होती हैं।
क्या software/IT service हमेशा export होती है?
नहीं। सामान्य recipient-location rule उपयोगी हो सकता है, लेकिन service का सही वर्गीकरण, recipient, intermediary relationship और विशेष place-of-supply clauses देखकर ही निर्णय करें।