
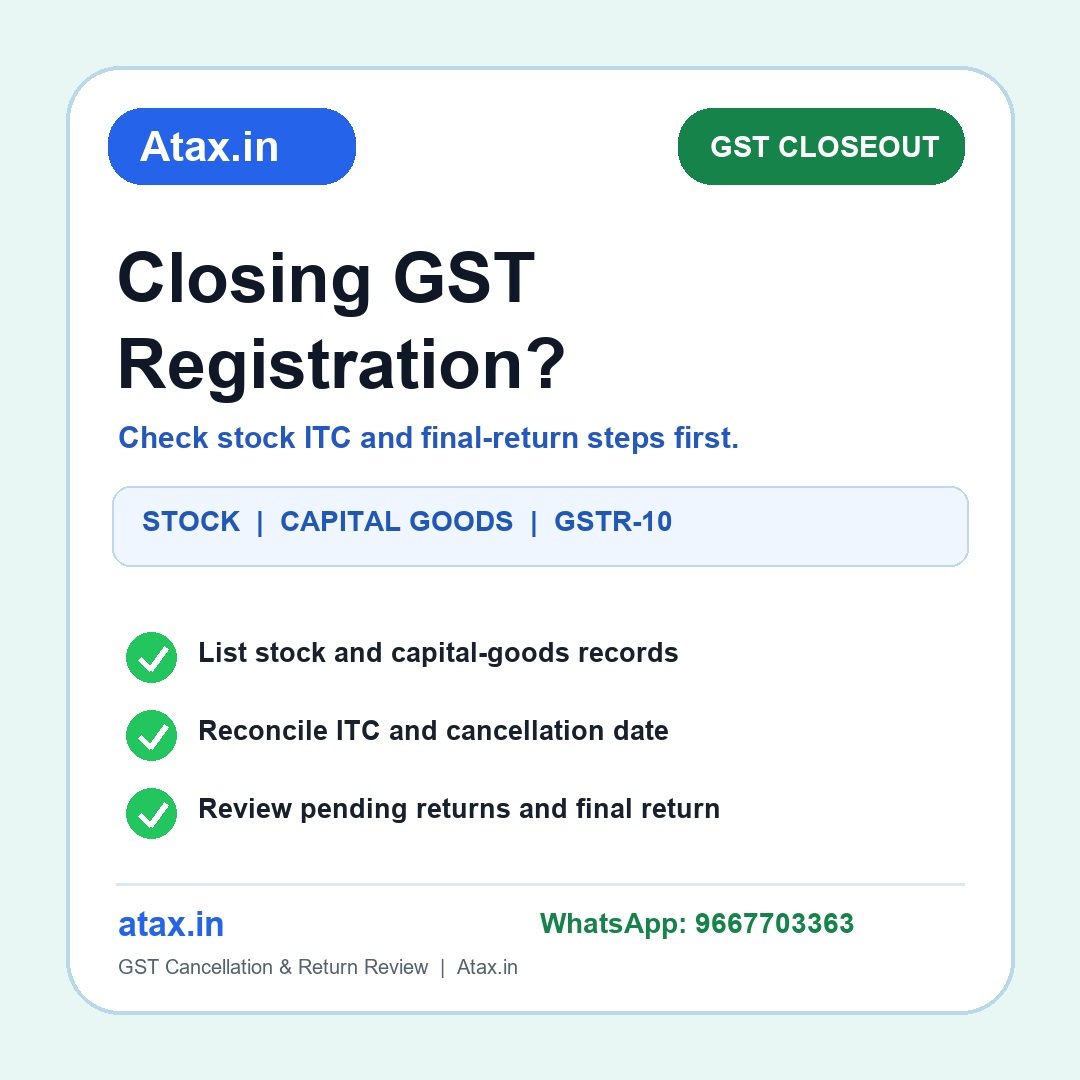
GST बंद करना हो तो पहले stock, capital goods और pending return का हिसाब साफ करें
दुकान या छोटा कारोबार बंद करने पर GST registration cancel करना सिर्फ portal पर form submit करना नहीं है। Cancellation की सही तारीख, बचा हुआ stock, पहले लिया ITC, capital goods और बाकी returns एक-दूसरे से जुड़े हैं। इन्हें पहले reconcile करने से application, अंतिम return और records के बीच mismatch घटता है।
सबसे पहले तय करें: सच में cancellation चाहिए?
अगर कारोबार बंद हो गया, transfer/merger हुआ, proprietor का निधन हुआ या आप अब registration के लिए liable नहीं हैं, तो facts के आधार पर cancellation देखी जा सकती है। अगर केवल business address, trade name, partner/director या constitution बदला है, तो cancellation के बजाय amendment या transferee-registration process सही हो सकता है। पहले reason और effective date तय करें; GSTIN की status-check और adviser की जाँच के बिना taxable supply बंद/चालू करने की धारणा न बनाएं।
Cancellation date से पहले stock की सूची बनाएँ
Closing date से ठीक पहले का stock count और valuation आधार बनता है। GST law में cancellation के समय कुछ inputs, semi-finished/finished goods और capital goods पर ITC-related amount या उन goods पर output tax में जो अधिक हो, उसका भुगतान लागू हो सकता है। हर asset पर बिना calculation एक ही तरीका न लगाएँ।
- कच्चा माल और resale goods: quantity, batch, purchase invoice, debit/credit note और अवशिष्ट मात्रा;
- अधबना माल और तैयार माल: item-wise quantity, cost/value और संबंधित input credit;
- computer, machine, furniture जैसे capital goods: invoice, ITC claim, खरीद तारीख और इस्तेमाल अवधि;
- यदि original stock invoice उपलब्ध नहीं: prevailing market price पर अनुमान संबंधी नियम और supporting working देखें;
- CGST/SGST/IGST/cess को अलग-अलग reconcile करके liability worksheet बनाएँ।
Rule 44 में stock का ITC संबंधित invoices के आधार पर और capital goods का remaining useful life (सामान्यतः 5 वर्ष) के आधार पर pro-rata निर्धारित करने का तरीका दिया गया है। Actual liability facts, applicable rule text और tax records देखकर निकाली जानी चाहिए।
एक सरल उदाहरण: दुकान के आखिरी दिन पर
मान लें किराना व्यापारी की दुकान बंद होने पर कुछ साबुन, पैक्ड सामान, आधे तैयार gift hampers और एक barcode printer बचा है। केवल “सारा माल बेच दिया” लिखना पर्याप्त नहीं: stock register को physical count और purchase invoices से मिलाएँ; hampers में लगे inputs को जाँचें; printer पर लिया credit और उसकी उम्र देखें। अगर पुराना invoice नहीं मिलता, तो अनुमान का आधार लिखें और market-price support रखें। यहाँ कोई निश्चित रकम नहीं दी जा रही, क्योंकि rate, credit history, quantity और transfer/sale facts हर file में अलग होते हैं।
Application और final return की sequence
- कारोबार बंद/transfer/eligibility change का evidence और प्रस्तावित effective cancellation date तय करें।
- GST portal application में stock, capital goods और संबंधित liability/payment की सही जानकारी दें। Rules में cancellation application के साथ यह विवरण शामिल करने की बात है; applicable timing और exception अपनी स्थिति पर जाँचें।
- जितने tax periods के returns बाकी हैं, उन्हें cancellation के आसपास reconcile करें। Cancellation पुराने tax dues और पहले की obligations को समाप्त नहीं करती।
- अगर Section 45 के तहत final return लागू है, तो GSTR-10 records तैयार करें और portal पर दिख रही due date/order के अनुसार file करें।
- ARN, cancellation order, filed returns, payment challans और stock worksheet को एक digital folder में रखें।
सरकारी GST portal manual application में cessation/closure के कारण पर date, stock और liability भरने के steps दिखाता है; अधिकारी review के बाद निर्णय लेते हैं। इसलिए application दाखिल होना approval का प्रमाण नहीं है।
Application से पहले ये documents जोड़ें
- GST registration certificate, latest portal status और cancellation का कारण बताने वाला प्रमाण;
- stock register, physical count sheet, purchase invoices, credit/debit notes और valuation working;
- capital goods register, purchase invoice, claimed ITC ledger और asset-use period;
- last filed GSTR-1/3B, books sales/purchase summary, e-invoice/e-way bill records जहाँ लागू हों;
- electronic cash/credit ledger, pending tax/interest/late fee और payment challans;
- closure/transfer/merger documents, board/partner resolution या death/succession records जहाँ लागू हों;
- application acknowledgement, officer notice/reply, cancellation order और final-return acknowledgement।
बार-बार होने वाली गलतियाँ
- effective cancellation date और actual last business day अलग-अलग रखना, पर books update न करना;
- physical stock count के बिना अंदाज़े से ITC reversal भरना;
- capital goods की पूरी पुरानी ITC को फिर से payable मान लेना या उल्टा बिल्कुल ignore कर देना;
- pending returns/dues को cancellation के बाद अपने-आप समाप्त समझना;
- GSTR-10 हर taxpayer को लागू मान लेना—Section 45 के अंतर्गत किसे final return देना है, पहले जाँचें;
- application acknowledgement को cancellation order मान लेना और बीच की अवधि की return obligations भूलना;
- GSTIN बंद करने से पहले customer advances, credit notes, unsold stock transfer और दूसरे GST registrations के असर को न देखना।
FAQ
क्या business बंद करने के दिन ही GSTIN cancel हो जाता है?
नहीं। Application, effective date और proper officer का order/status अलग-अलग देखना होता है। Portal acknowledgement और final order सुरक्षित रखें।
क्या बचा हुआ हर सामान बेचने से पहले tax भरना होगा?
प्रश्न stock की प्रकृति, cancellation date, ITC लिया गया था या नहीं, और Section 29(5)/Rule 44 की गणना पर निर्भर है। Goods-wise worksheet बनवाएँ; एक universal answer लागू नहीं होता।
क्या cancellation से पुरानी returns और tax dues खत्म हो जाते हैं?
नहीं। Section 29(3) के अनुसार cancellation से पहले की अवधि की tax/other dues liability और कानून के तहत obligations प्रभावित नहीं होतीं। Pending periods अलग से निपटाएँ।
GSTR-10 सभी cancelled GST registrations को file करना होता है?
Section 45 के तहत final-return applicability जाँचें। यदि लागू है, portal पर दिखती due date और आपके cancellation order से मिलाकर GSTR-10 की तैयारी करें।
Application reject या notice आ जाए तो?
Notice/deficiency का कारण, reply window और stock/return records साथ देखकर तथ्यात्मक response तैयार करें। Deadline चूकने से पहले GST practitioner/Atax office से file review कराएँ।